How to Insure a Warehouse Staffing Agency: Requirements Guide
Quick Summary
Warehouse staffing agency insurance requirements usually include workers' compensation, general liability, professional liability, employment practices liability, commercial auto if staff drive company vehicles, and umbrella coverage. Clients typically ask for certificates of insurance before placing workers, and contract limits often exceed state minimums.
- Workers' compensation pays medical bills and lost wages when a placed worker is hurt on the job.
- General liability covers claims from third parties, such as a visitor injured at a client site.
- Professional liability protects your agency if a placement error causes a client financial loss.
- Check client contracts for required limits, since they often exceed what state law requires.
- Keep accurate job classification records, because misclassifying workers can lead to audits and penalties.
Table of Contents
- What Insurance a Warehouse Staffing Agency Needs
- Staffing Agency Workers' Compensation Insurance for Warehouse Placements
- Who Is Responsible After a Warehouse Injury
- Staffing Agency General Liability Insurance and Coverage Limits
- Staffing Agency Insurance Certificate Requirements Clients Expect
- Warehouse-Specific Hazards, Job Classifications, and Premium Drivers
- Business Insurance for Staffing Agency Operations: Professional Liability and Beyond
- Building Your Warehouse Staffing Insurance Checklist and Next Steps
- Frequently Asked Questions
What Insurance a Warehouse Staffing Agency Needs
Last Updated: November 15, 2026
Warehouse staffing agencies carry more insurance risk than most people expect. You place workers on other companies' loading docks, forklifts and racking, and the injuries and damage that follow can land on your balance sheet. Knowing which policies to carry is the first step to insuring your agency properly.
Warehouse staffing agency insurance requirements usually cover a core set of policies. Most clients will ask to see them before they sign a contract. The main ones are:
- Workers' compensation insurance for your placed employees
- General liability insurance for injuries or damage to third parties
- Professional liability (errors and omissions) coverage
- Employment practices liability insurance
- Commercial auto insurance if your staff drive company vehicles
- Umbrella or excess liability coverage for higher limits
Each policy covers a different type of loss. Workers' compensation pays medical bills and lost wages when a worker is hurt on the job. General liability covers claims from third parties, such as a visitor slipping on a wet floor at a client site. Professional liability protects you if a placement error causes a client financial loss.
A common mistake is buying only the minimum a state requires. Clients often ask for higher limits in their contracts, so check those requirements before you buy.
Staffing Agency Workers' Compensation Insurance for Warehouse Placements
Workers' compensation is the policy warehouse clients ask about first. It pays for medical care and lost wages when a placed worker is injured on the job, and most states require it for any employer with staff.
Warehouse work carries higher injury rates than many industries. Lifting, forklift operation and loading dock work all produce common injuries. Your premium will reflect the job classifications your workers fall into, so keep accurate records of where each worker is placed.
Watch out: misclassifying workers to lower your premium can lead to audits, back premiums and penalties.
Who Is Responsible After a Warehouse Injury
When a placed worker is hurt in a warehouse, responsibility is shared across three parties: your staffing agency, the host employer, and the worker. The fastest way to create a dispute is to leave those roles vague in the contract. The fastest way to resolve a claim is to define them before the first shift.
The staffing agency's role. As the employer of record, your agency typically carries the workers' compensation policy that responds to the injury, pays medical bills, and coordinates wage replacement. That means your agency usually owns the first report of injury, the carrier notification, and the initial claims file.
The host employer's role. The warehouse controls the physical worksite, so it usually owns site-specific safety orientation, equipment condition, and hazard correction. If a forklift has a faulty horn or a dock plate is unsecured, that is the host's responsibility to fix and document. The host also typically investigates the incident on its side, preserves any video, and provides a site incident report to your agency. Your contract should require the host to notify your agency within a set window, commonly 24 hours, and to cooperate with the carrier investigation.
The worker's role. The placed employee is responsible for following training, using required personal protective equipment, and reporting hazards and injuries promptly. A common pattern is to require workers to report any injury, even a minor one, before the end of the shift. Late reporting is one of the most common reasons a claim becomes contested.
Claims handling and return-to-work. After the report, your carrier or third-party administrator opens the claim, investigates, and coordinates medical treatment. The host employer often has light-duty work available, and a written return-to-work agreement between your agency and the host can shorten lost time and reduce claim cost. Put the return-to-work process in the contract: who offers modified duty, who approves it, and how the worker's restrictions are communicated.
What to put in writing. At minimum, the staffing agreement should address:
- Who reports the injury to the carrier and within what timeframe
- Who investigates and preserves evidence such as video and equipment records
- Who provides safety orientation and personal protective equipment
- How return-to-work and modified duty are coordinated
- How the parties share information during an open claim
Watch out: if the contract is silent on reporting and investigation duties, the host and agency can each assume the other is handling it, and the delay can complicate the claim and the client relationship.
Keep a written record of every placement, including safety briefings, equipment issued, and incident follow-up. That record is what your carrier will ask for when a claim is filed, and it is what your client will point to when responsibility is questioned.
Staffing Agency General Liability Insurance and Coverage Limits
General liability insurance covers claims from people outside your company, such as client employees or visitors who are injured or whose property is damaged. Client requirements vary by contract, so check the limits each one specifies.
Check your limits against each client contract. If a contract asks for higher limits than your policy provides, an umbrella policy can fill the gap at a lower cost than raising every underlying policy.
Staffing Agency Insurance Certificate Requirements Clients Expect
Before a warehouse client places workers, they will typically request a certificate of insurance (COI). This document confirms your active policies, coverage types and limits. Many clients also ask to be named as an additional insured, which extends certain coverage to them.
Ask your broker for COIs that match each client's exact requirements. A COI that shows the wrong limits or leaves out a required policy can delay placements. Keep a current copy on file and update it whenever a policy renews.
Warehouse-Specific Hazards, Job Classifications, and Premium Drivers
Warehouses are not a single risk category. A picker working a quiet day shift and a forklift operator working a loading dock around moving trailers carry very different exposures, and your workers' compensation classifications and premiums should reflect that difference.
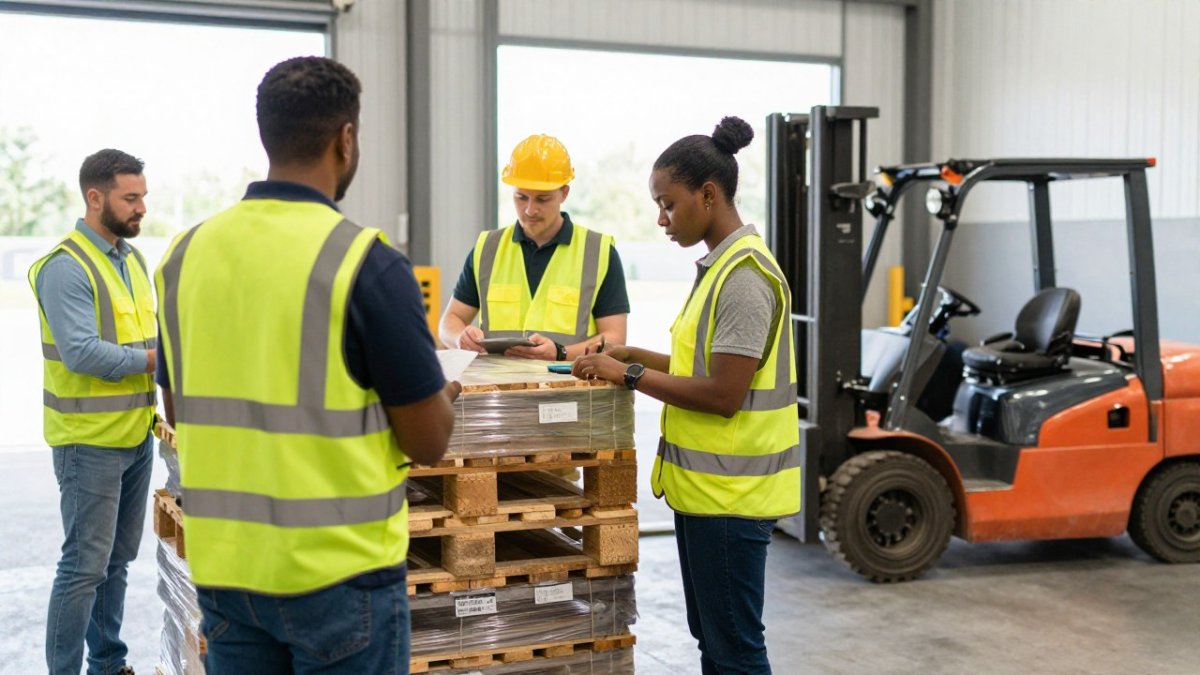
The hazards that drive warehouse claims. The most common warehouse injury patterns are forklift and powered industrial truck incidents, falling loads from racking, repetitive strain from picking and packing, slips and falls on loading docks, and struck-by injuries in congested aisles. Shift work adds fatigue-related risk, and cold-storage or freezer environments add slip and cold-exposure concerns. Each of these maps to a different classification and a different set of controls.
Job classifications and why they matter. Workers' compensation carriers assign classifications based on the work performed, not the job title. A worker classified as a general laborer or picker is rated differently from a forklift operator or a dock worker. If your payroll records show a worker operating a forklift but the policy classifies the role as light packing, the carrier can assess back premiums and penalties at audit.
What drives your premium. Several factors move your cost:
- Payroll by classification, since premium is generally a rate per $100 of payroll
- Claims history and your experience modification rate
- The safety controls you require and document at each worksite
- Deductibles and the limits you choose
- The mix of shift work and overtime in your placements
Contract wording clients will ask about. Warehouse clients commonly request that they be named as an additional insured on your general liability policy, that your policy be primary and noncontributory, and that you waive subrogation against the client. They may also set certificate deadlines, such as requiring a current certificate of insurance before the first placement and at each renewal.
Coverage limits in practice. Warehouse contracts set their own general liability and umbrella limits, so confirm the figures each client requires. Actual requirements depend on the contract, state law, and insurer underwriting, and a broker should confirm what your program can support before you sign.
Safety controls that support insurability. Documented forklift certification, pre-shift equipment inspections, incident reporting, and host-site safety coordination all give your carrier evidence that you manage the risk. Keep those records per placement, not just per client, so you can show exactly what training and equipment each worker received.
Watch out: promising a client additional-insured status or a waiver of subrogation your policy does not provide can leave you in breach of contract and exposed on a claim. Verify the wording with your broker before it goes into a staffing agreement.
The table below summarises the main warehouse injury patterns and the job classifications and controls that go with them.
| Hazard | Typical exposure | Control that supports insurability |
|---|---|---|
| Forklift and powered truck incidents | Operators and nearby staff | Documented forklift certification |
| Falling loads from racking | Pickers and aisle workers | Pre-shift equipment inspections |
| Repetitive strain | Picking and packing | Incident reporting |
| Slips and falls on docks | Loading dock workers | Host-site safety coordination |
| Struck-by injuries | Congested aisles | Per-placement training records |
Business Insurance for Staffing Agency Operations: Professional Liability and Beyond
Professional liability, also called errors and omissions coverage, protects your agency when a placement mistake causes a client loss. Examples include sending an unqualified worker or failing to verify certifications. Employment practices liability covers claims such as wrongful termination or discrimination, which can arise even with temporary staff.
Some agencies also carry commercial auto, cyber liability and umbrella coverage. Review your full program each year as your client base and placement volume grow.
Building Your Warehouse Staffing Insurance Checklist and Next Steps
Use this checklist when you review your insurance program:
- Workers' compensation active in every state where you place workers
- General liability limits that meet each client contract
- Professional liability and employment practices coverage in place
- Umbrella or excess coverage for higher contract limits
- Current certificates of insurance on file for each client
- Job classifications reviewed against actual placements
- Written safety and training records for every worker
Insurance for a warehouse staffing agency is complex, and requirements change by state and by client. Review your program with a licensed insurance broker who knows staffing risk. Start from your problem and build a safer, more insurable operation.
Frequently Asked Questions
Does a warehouse staffing agency need workers' compensation insurance?
Yes. In most jurisdictions an agency that employs temporary workers must carry workers' compensation coverage for them, because the agency is typically the employer of record. The requirement applies regardless of which client site the worker is placed at. Coverage rules, required limits and penalties for going uninsured vary by state or province, so confirm the requirements where your workers are placed. Clients usually ask for proof of this coverage before any worker starts on their floor.
Who is responsible for workers' compensation when a temp worker is injured?
The staffing agency, as the employer of record, normally files the workers' compensation claim and carries the policy that pays benefits. The host client may also share responsibility depending on contract language, supervision, and the worksite hazard involved. Agencies should document incidents immediately, report them to their carrier on time, and make sure contracts define who handles claims and how costs are allocated. Clear contract terms reduce disputes after a warehouse injury.
What insurance certificates should a warehouse client request from a staffing agency?
Clients typically request a certificate of insurance (COI) showing workers' compensation, commercial general liability, and often professional liability or errors and omissions coverage. Many also require additional insured status on the general liability policy and a waiver of subrogation. The certificate should show current policy periods and limits that match the client contract. Check that certificates are renewed on schedule, since an expired COI can put a placement on hold.
What does staffing agency general liability insurance cover in a warehouse?
General liability insurance covers third-party bodily injury and property damage claims arising from the agency's operations, such as a placed worker damaging a client's inventory or injuring a visitor. It does not replace workers' compensation, which covers the worker's own injuries. Coverage limits should match what client contracts require, and policy limits and exclusions should be reviewed against the actual warehouse operations you supply labour for.
